How Does Ready-to-Drink Coffee Fit the Wider Coffee Market?
Ready-to-drink coffee holds only around ten percent of China's coffee consumption market, yet it has grown faster than soft drinks and bottled water, with its market size approaching ten billion yuan. Nestlé leads the segment, Starbucks follows, and COSTA, Wahaha, Uni-President, Yili, Tims, Nongfu Spring and Coca-Cola all now compete there.
Canned and bottled coffee entered China as early as 1998, when foreign brands such as Suntory pushed into coffee shops and supermarkets. In 2018 ready-to-drink coffee accounted for 10.1 percent of total consumption value. As freshly ground coffee wages a price war, ready-to-drink brands face pressure to defend their space and move toward specialty and premium products.
The domestic coffee consumer market continues to expand, with the three major categories of instant, freshly ground, and ready-to-drink each having their own track. Among them, ready-to-drink coffee, although accounting for only about ten percent of market share and appearing relatively low-key, has in recent years grown far faster than the overall levels of soft drinks and bottled water, with its market size approaching ten billion. Giants such as Nestlé and Starbucks have been increasing their investments in the segment, and consumers' demand for ready-to-drink, high-cost-performance products is also driving the category's expansion. At the same time, trends toward specialty and premiumization are beginning to emerge, and prices are rising accordingly. Whether ready-to-drink coffee can find its own space for survival under the squeeze of low-price involution in freshly ground coffee is worth an in-depth discussion.
The scale of domestic coffee consumption continues to expand, and the three major categories of instant, specialty freshly ground, and ready-to-drink have all achieved considerable progress.
Compared with the other two categories, ready-to-drink coffee has a noticeably lower presence, occupying only about ten percent of the entire coffee consumption market. However, along with the continuous rise in coffee demand, the ready-to-drink coffee sector has gradually heated up, and the entire track shows considerable development prospects.
Looking back at history, ready-to-drink coffee's entry into the Chinese market can be traced back as early as 1998, when foreign brands such as Suntory quickly expanded into retail channels such as coffee shops and supermarkets, thereby opening up the consumer market for canned and bottled coffee. After that, the domestic coffee market developed rapidly, and a large number of brands rushed into the ready-to-drink coffee track.
At present, companies such as Nestlé, Starbucks, COSTA, Wahaha, Uni-President, Yili, Tims, Nongfu Spring, and Coca-Cola have all established a presence in this space. Judging from the current competitive landscape, Nestlé sits firmly in first place thanks to its first-mover advantage, while Starbucks follows closely in second.
According to incomplete statistics, in 2018 China's ready-to-drink coffee market accounted for 10.1% of total consumption value, while instant and freshly ground coffee accounted for 71.8% and 18.1% respectively. Ready-to-drink coffee may not seem to occupy the mainstream in the coffee market, but with consumption diversification and product differentiation, the market share of ready-to-drink coffee is gradually expanding.
Driven jointly by the consumer side and the industry side, the ready-to-drink coffee category continues to grow rapidly. According to data from LeadLeo Research Institute, from 2017 to 2021, China's ready-to-drink coffee market doubled in scale with a compound growth rate of 19.3%, reaching 9.64 billion, and the growth space in the coming years is expected to remain considerable. It is worth mentioning that the growth rate of the ready-to-drink coffee market far exceeds the overall growth rate of soft drinks and bottled water.
From the consumer's perspective, the most valued factors when choosing ready-to-drink coffee are concentrated in aspects such as consistency of taste, no brewing required, drinking anytime and anywhere, and rapid refreshment. These characteristics precisely match the core demands of people living in today's fast-paced society. At the same time, consumers also pursue high cost performance. Some lovers of freshly made coffee have begun trying ready-to-drink coffee; while satisfying caffeine needs, large volume and low price are among the factors that make ready-to-drink coffee a preferred choice.
As the public's requirements for coffee quality gradually rise, the direction toward specialty and premiumization of ready-to-drink coffee is becoming increasingly clear. According to the "2020 Ready-to-Drink Coffee Innovation Trend Report," 45% of consumers in the ready-to-drink market hope for the use of high-quality milk sources, while 44% of users hope for the selection of high-quality coffee beans. To a certain extent, this also reflects that the premiumization of ready-to-drink coffee will become a trend in the future.
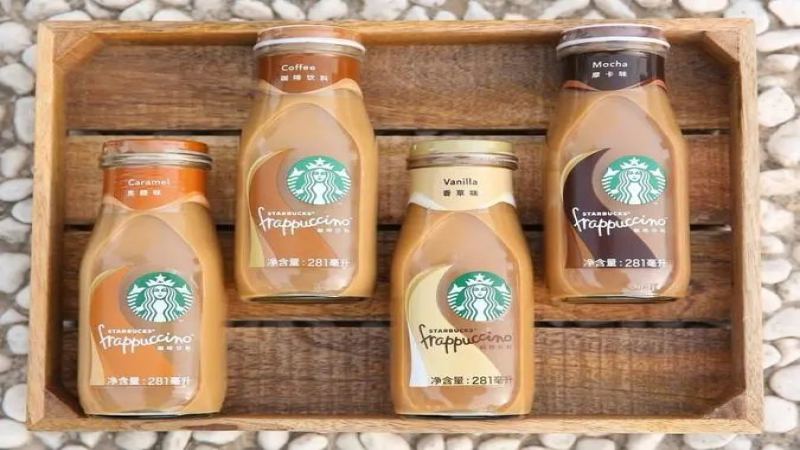
However, once ready-to-drink coffee advances toward specialization, price increases are almost inevitable. Taking products originally priced at around 5 yuan as an example, after raising the banner of upgraded ingredients and craftsmanship, prices often jump to the 10 to 16 yuan range. For example, a 281ml Starbucks Frappuccino coffee is priced at about 16 yuan, already on par with a cup of freshly ground coffee. Under such circumstances, how many consumers are truly willing to pay? Therefore, formulating a reasonable pricing strategy for ready-to-drink coffee is crucial to the long-term development of the entire category.
The fact that ready-to-drink coffee can rank among high-growth beverage categories is largely due to the successive entry of industry giants. Although competition among brands is becoming increasingly intense, it has also pushed ready-to-drink coffee into a brand-new stage of competition. In the future, products that are premiumized, specialized, and highly playable will also better meet the public's expectations.
The above content is compiled by CoffeeHunters, a coffee news website.